Helping People Discover Their Best Options Through...

The Rebe Homes Team helps our clients by providing...

Information with clear interpretation,
Judgment rooted in experience,
Insight that protects,
Conscious guidance based on integrity,
Meaning behind every decision,
Inspiration that encourages,
Relationships with service.

Friday, August 28, 2015

52% Likely to Buy in the Next 5 Years!! Are You?


52% Likely to Buy in the Next 5 Years!! Are You? | Keeping Current Matters

According to the recently released BMO Harris Bank Home Buying Report, 52% of Americans say they are likely to buy a home in the next five years. Americans surveyed for the report said they would be willing to pay an average of $296,000 for a home and would average a 21% down payment. The report also had other interesting revelations.

Those Looking to Buy
  • 74% of those looking to buy a new home will consult a real estate agent
  • 59% said they will visit online real estate websites
  • 37% will seek recommendations from friends and family
  • 78% plan to get pre-approved before seriously searching for a home
Those Who Already Own
  • 75% of current home owners set a budget before looking for a home. 16% ended up spending less while 13% went over their budget.
  • 63% of American homeowners spent under six months looking for a new home before they made a purchase.
  • 8% bought their home without participating in an active real estate search - or even any plan to buy at all - because a specific property caught their attention.
The last point is very interesting: Of those that purchased a home, 8% bought “without any plan to buy at all”. A property caught their attention and they acted on it.

Why are More People not Planning their Next Move?

Why are people that are considering a move not putting their home search to a plan, and instead, buying only when a property catches their attention? A recent article by Fannie Mae may give us that answer, there is evidence that a large numbers of homeowners are dramatically underestimating the equity they have in their current home. The report explains:

“Homeowners may be underestimating their home equity. In particular, if homeowners believe that large down payments are now required to purchase a home, then widespread, large underestimates of their home equity could be deterring them from applying for mortgages, selling their homes, and buying different homes.”

Bottom Line


Perhaps it is time to sit with a real estate professional to determine the actual equity you have in your house and take a look at the opportunities that currently exist in the real estate market. This may be the perfect time to move-up, move-down or buy that vacation home your family has always wanted.

Wednesday, August 26, 2015

Should I Wait to Put Down a Bigger Down Payment?


Should I Wait to Put Down a Bigger Down Payment? | Keeping Current Matters

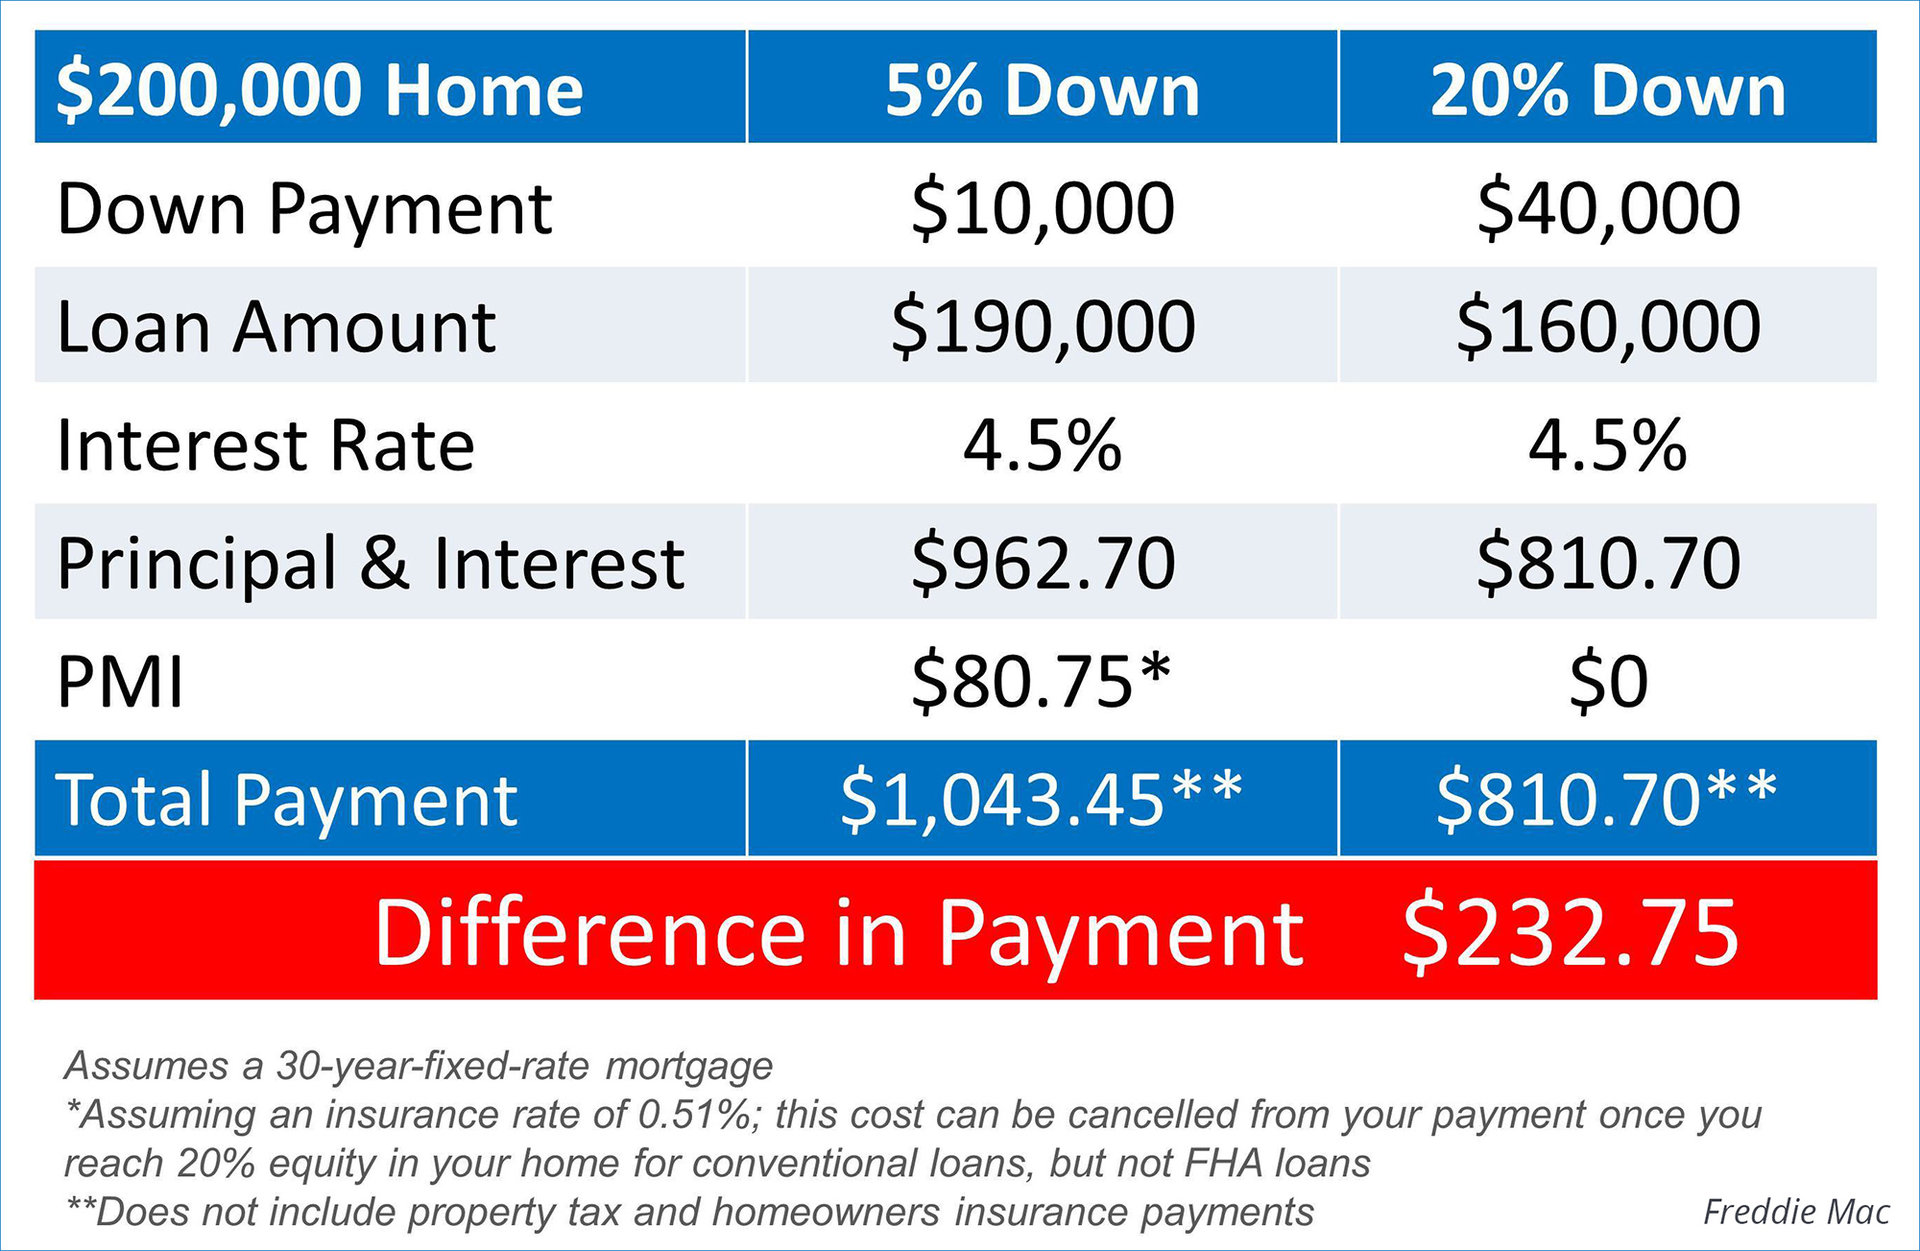
Some experts are advising that first time and move-up buyers wait until they save up 20% before they move forward with their decision to purchase a home. One of the main reasons they suggest waiting is that a buyer must purchase private mortgage insurance if they have less than the 20%. That increases the monthly payment the buyer will be responsible for.

In a recent article, Freddie Mac explained what this would mean for a $200,000 house:

Difference Between a 5% and 20% Down Payment | Keeping Current Matters

However, we must look at other aspects of the purchase to see if it truly makes sense to wait.
Are you actually saving money by waiting?

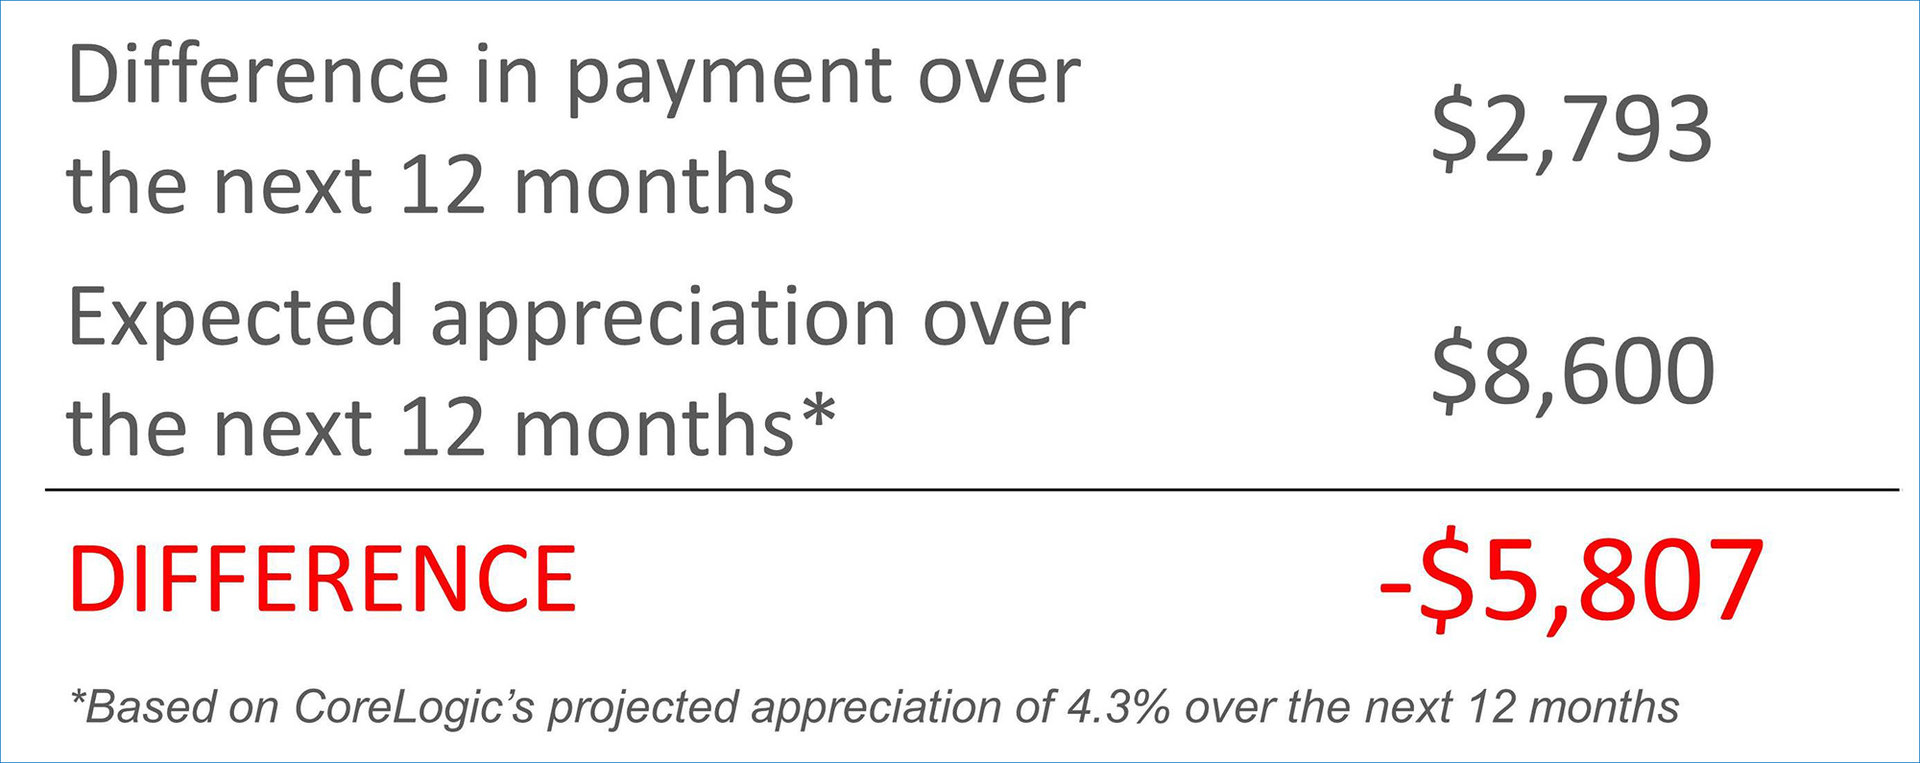
CoreLogic has recently projected that home values will increase by 4.3% over the next 12 months. Let’s compare the extra cost of PMI against the projected appreciation:

PMI vs Appreciation | Keeping Current Matters

If you decide to wait until you have saved up a 20% down payment, the money you would have saved by avoiding the PMI payment could be surpassed by the additional price you eventually pay for the home. Prices are expected to increase by more than 3% each of the next five years.

Saving will also be more difficult if you are renting, as rents are also projected to increase over the next several years. Zillow Chief Economist Dr. Svenja Gudell explained in a recent report:

"Our research found that unaffordable rents are making it hard for people to save for a down payment ... There are good reasons to rent temporarily – when you move to a new city, for example – but from an affordability perspective, rents are crazy right now. If you can possibly come up with a down payment, then it's a good time to buy a home and start putting your money toward a mortgage."

Laura Kusisto of the Wall Street Journal recently agreed with Dr. Gudell:

“For some renters there may be a way out: Buy a house. Mortgages remain very affordable.”

Mortgage rates are expected to rise…

Freddie Mac is projecting that mortgage interest rates will increase by almost a full percentage point over the next 12 months. That will also impact your mortgage payment if you wait.

Bottom Line


Sit with a real restate or mortgage professional to truly understand whether you should buy now or wait until you save the 20%.

Don’t Get Caught In The Renter’s Trap

Don't Get Caught In The Renter's Trap | Keeping Current Matters

There are many benefits to homeownership. One of the top ones is being able to protect yourself from rising rents and lock in your housing cost for the life of your mortgage.

The National Association of Realtors (NAR) released their findings of a study in which they studied “income growth, housing costs and changes in the share of renter and owner-occupied households over the past five years in metropolitan statistical areas throughout the US.”

Don’t Become Trapped

The study revealed that over the last five years a typical rent rose 15% while the income of renters grew by only 11%. If you are currently renting, this disparity in growth could get you caught up in a cycle where increasing rents continue to make it impossible for you to save for a necessary down payment.

The average renter in the United States pays 30% of their income on housing compared to that of a homeowner who can expect to spend 15%.

In many metro areas the percentage of income spent on housing is even higher and continues to rise every year. Like in San Francisco, CA, where the average renter spends 59% of their monthly income on housing or nearly 65% in Boston, MA.

Homebuyers who purchased their home over the same five-year period locked in their housing costs and were able to grow their net worth as home values have increased and their mortgage balances have gone down.

Know Your Options

Perhaps, you have already saved enough to buy your first home. HousingWire reportedthat analysts at Nomura believe:

“It’s not that Millennials and other potential homebuyers aren’t qualified in terms of their credit scores or in how much they have saved for their down payment.

It’s that they think they’re not qualified or they think that they don’t have a big enough down payment.” (emphasis added)

As we have reported last week, over 60% of Millennials who recently bought a home put down less than 20%; 36% put down less than 5%. Your dream home may be more attainable than you ever imagined!

Bottom Line


Don’t get caught in the trap so many renters are currently in. If you are ready and willing to buy a home, find out if you are able. Have a professional help you determine if you are eligible to get a mortgage.

Friday, August 21, 2015

64.2% of Millennials Put Down Less than 20%


64.2% of Millennials Put Down Less than 20% | Keeping Current Matters

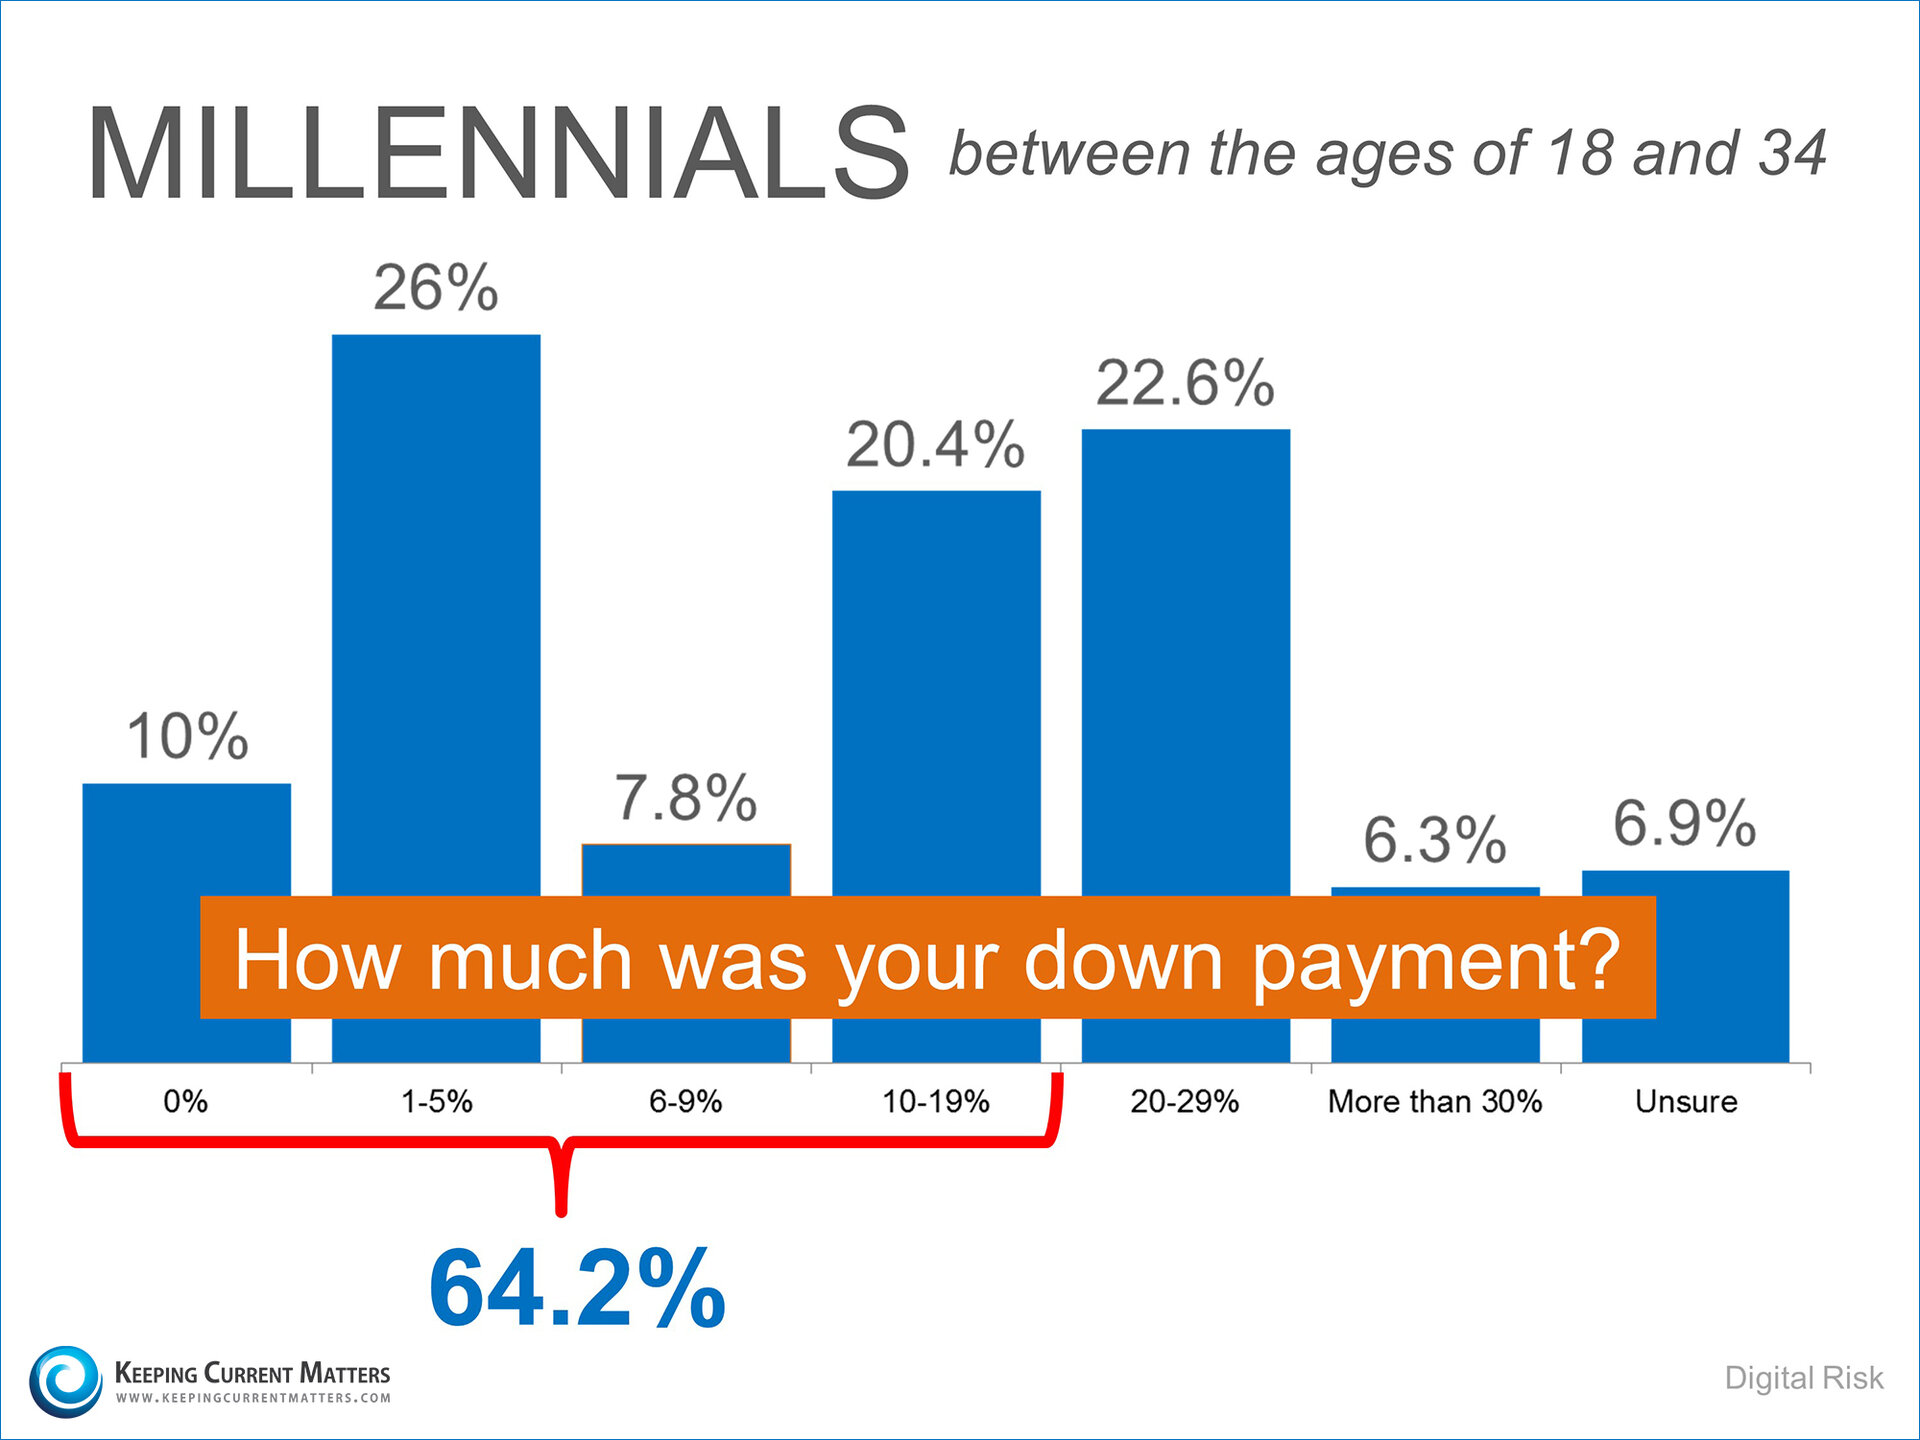
Digital Risk recently polled Millennials about the housing market. Among their findings was the fact that nearly two-thirds of the generation who have recently purchased a home, have done so with less than 20% down; with 36% putting down less than 5%!

Here is a graph detailing the results:

Millennial Down Payments | Keeping Current Matters

This means that more and more American’s between the ages of 18 and 34 stopped paying their landlord’s mortgage and started building their own family’s wealth.

Millennials aren’t the only ones taking advantage of lower down payments.

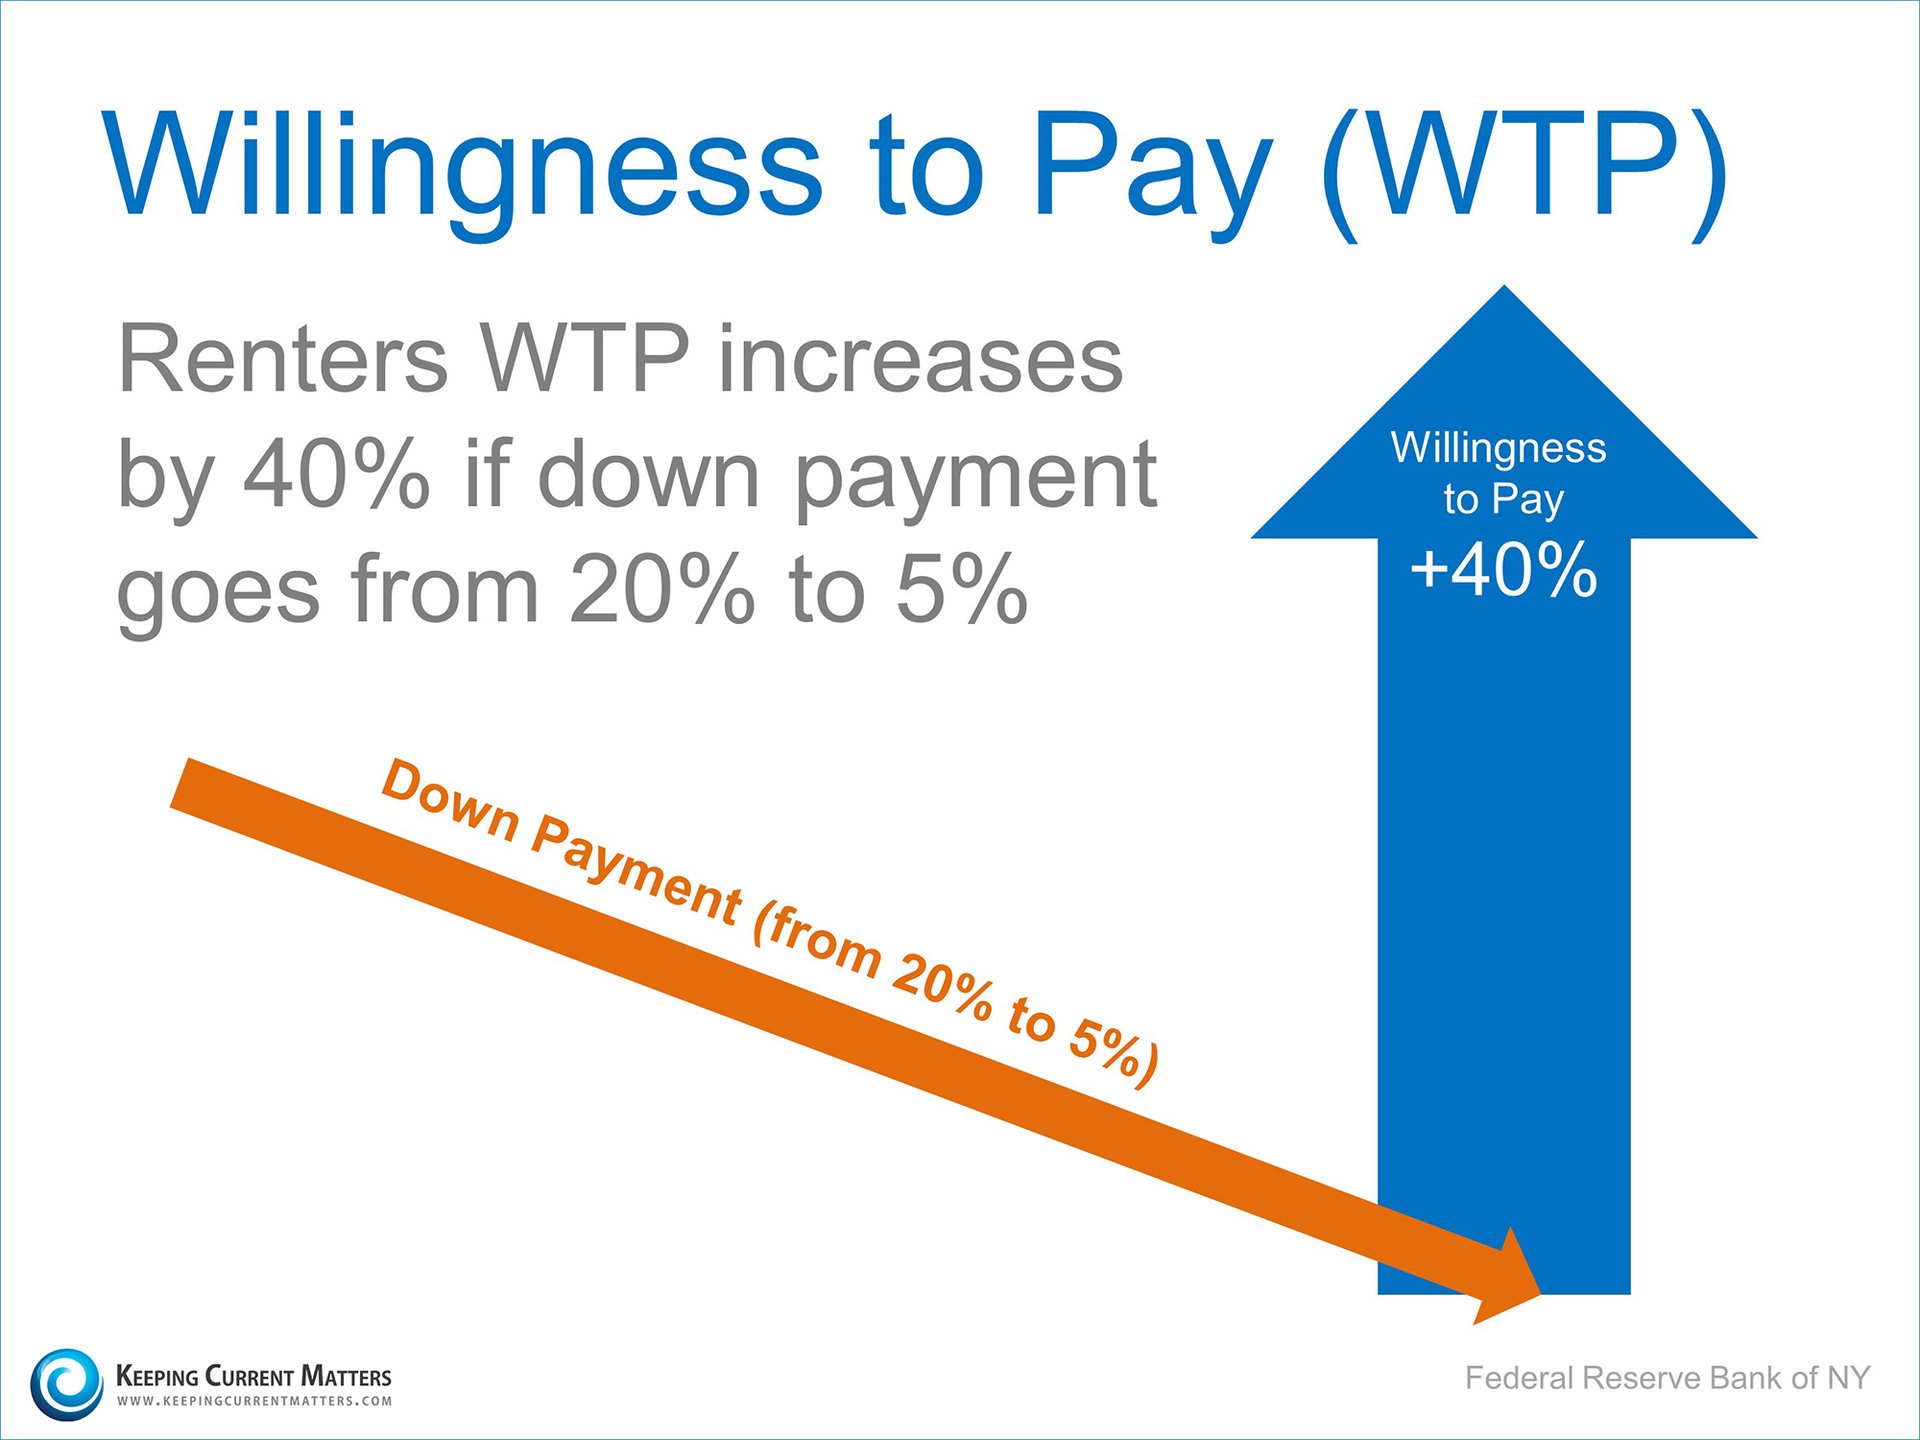
The Federal Reserve Bank of New York found that if the down payment required to purchase a home went from 20% to 5%, a renter’s Willingness To Pay (WTP) increased by 40%.

Willingness To Pay | Keeping Current Matters

The problem is that thirty-six percent of Americans still think a 20% down payment is always required when buying a home. Many renters may actually be able to enter the housing market sooner than they ever imagined with new programs that have emerged allowing less cash out of pocket.

Bottom Line


If you are one of the many renters now realizing that the home of your dreams is obtainable, contact a local real estate professional who can guide you through the process.

Real Estate Again Seen as Best Investment


Real Estate Seen As Best Investment Again | Keeping Current Matters

We are almost back to ‘pre-housing crash’ home values. The inventories of distressed properties (foreclosures & short sales) are shrinking dramatically. The economy is improving. The job numbers are headed in the right direction.

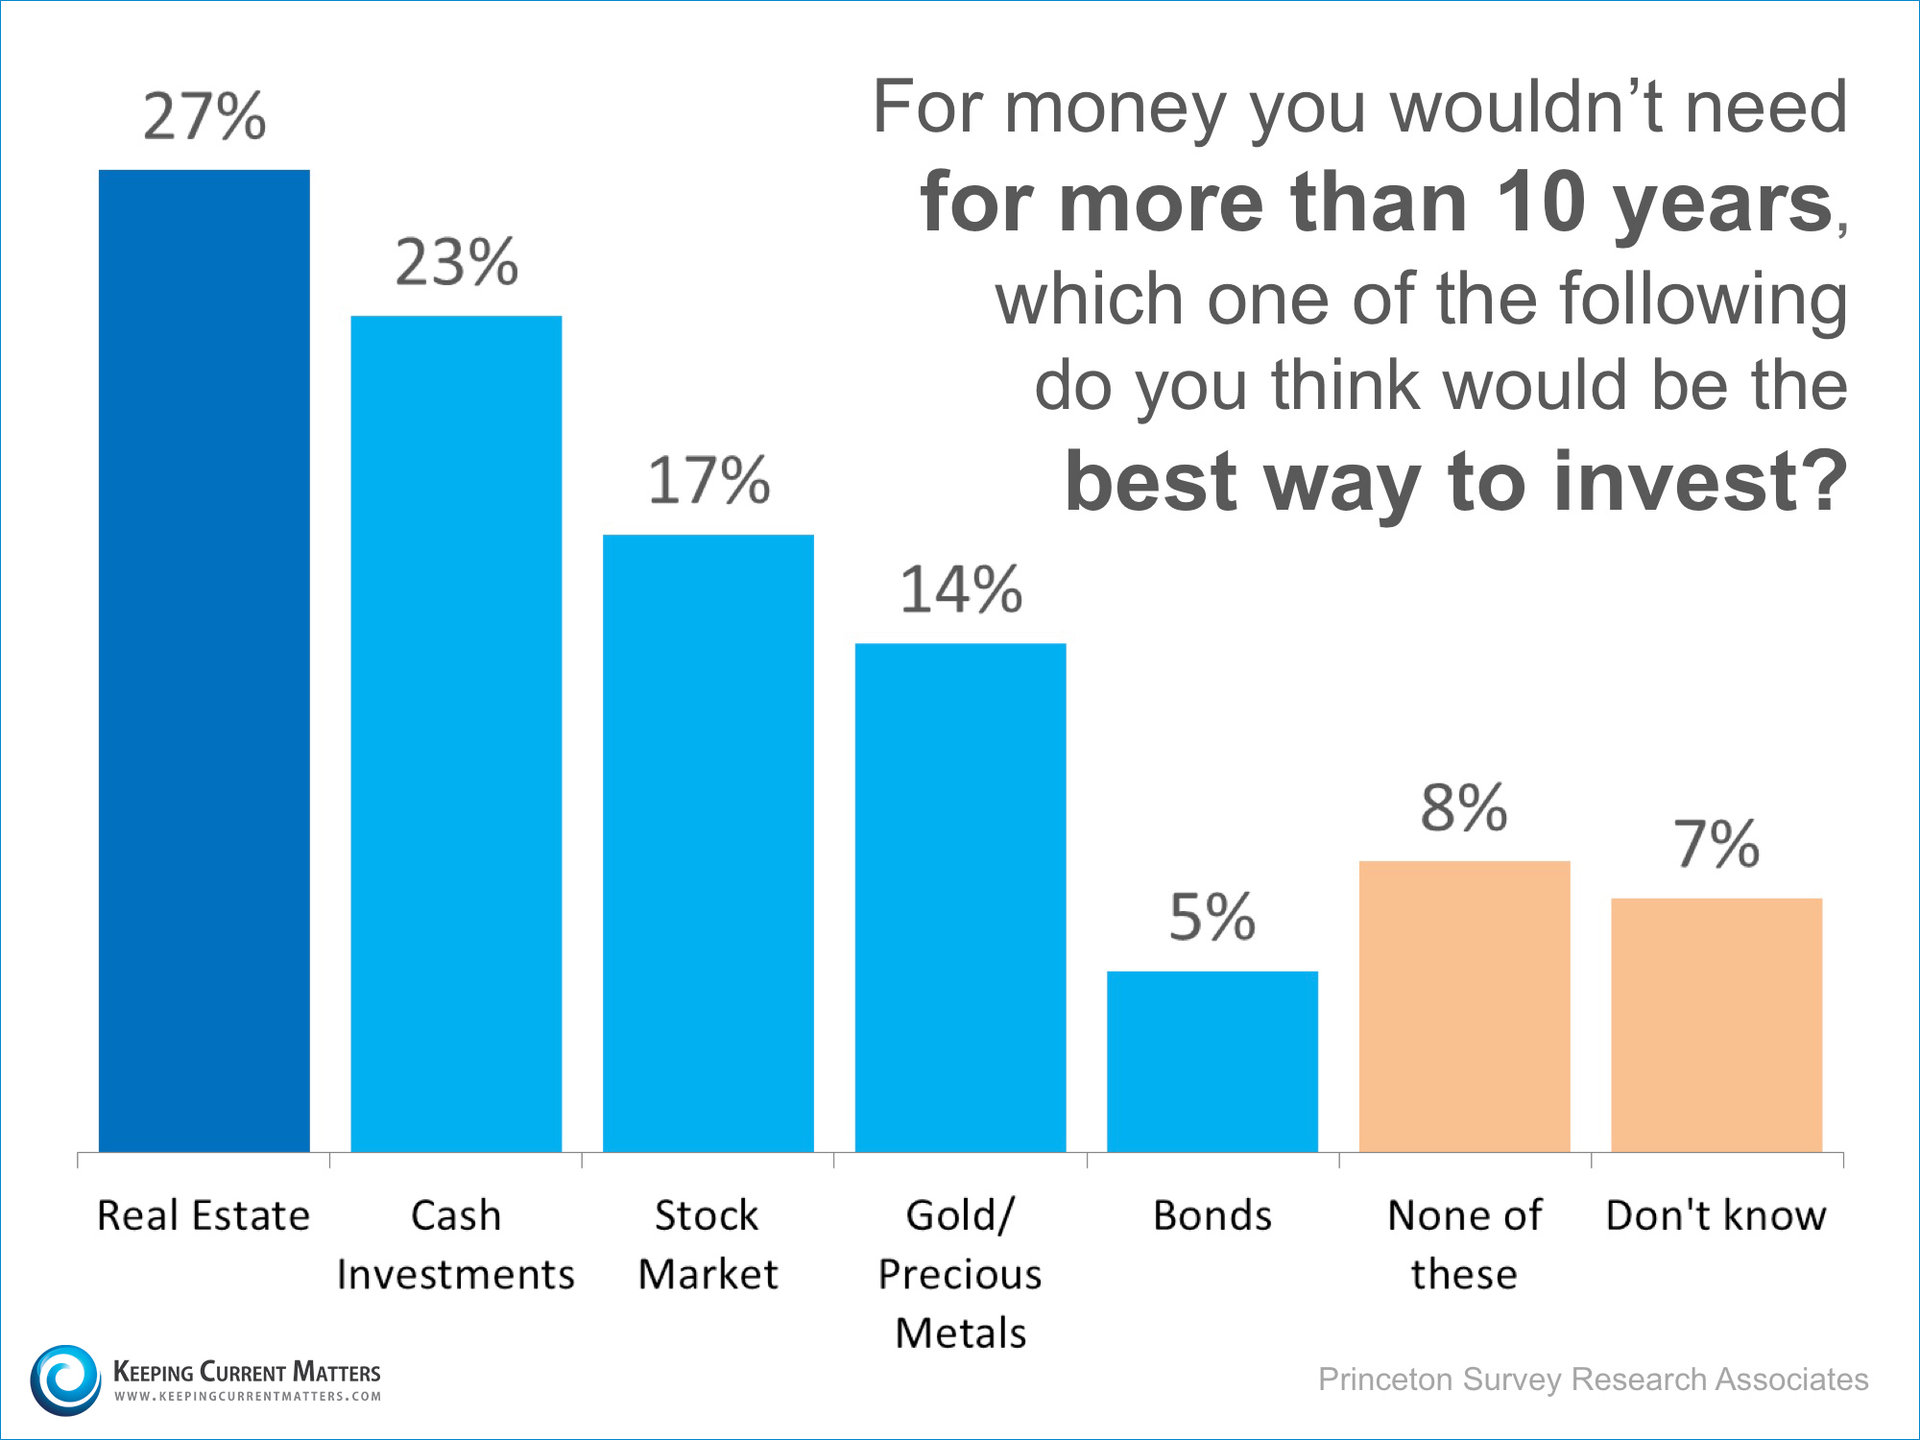
The big question that still remains: Have Americans regained their confidence in real estate as a worthy investment?

According to a survey conducted by Princeton Survey Research Associates, Americans have put real estate back into first place as the best of all investments.

Here are the results of the survey:

Best Investment | Keeping Current Matters

Bottom Line


Homeownership never lost its place as a key component of the American Dream for a host of financial and non-financial reasons. It is good to see that it has regained the top spot as best overall investment.

Home Values: Where Are They Headed Over The Next 5 Years?


Home Values: Where Are They Headed in the Next 5 Years? | Keeping Current Matters

Today, many real estate conversations center on housing prices and where they may be headed. That is why we like the Home Price Expectation Survey.

Every quarter, Pulsenomics surveys a nationwide panel of over one hundred economists, real estate experts and investment & market strategists about where prices are headed over the next five years. They then average the projections of all 100+ experts into a single number.

The results of their latest survey
  • Home values will appreciate by 4.1% in 2015.
  • The cumulative appreciation will be 18.1% by 2019.
  • That means the average annual appreciation will be 3.4% over the next 5 years.
  • Even the experts making up the most bearish quartile of the survey still are projecting a cumulative appreciation of 10.5% by 2019.

Individual opinions make headlines. We believe the survey is a fairer depiction of future values.

The REAL Reasons Americans Buy a Home

The Real Reasons Americans Buy A Home | Keeping Current Matters

We often talk about the financial reasons why buying a home makes sense. But often, the emotional reasons are the more powerful, or compelling reasons. The Joint Center for Housing Studies at Harvard University performs a study every year surveying participants for the reasons that American’s feel are most important in regards to homeownership.

The top 4 reasons to own a home cited by respondents were not financial.

1. It means having a good place to raise children & provide them with a good education

From the best neighborhoods to the best school districts, even those without children at the time of purchasing their home, may have this in the back of their mind as a major reason for choosing the location of the home that they purchase.

2. You have a physical structure where you & your family feel safe

It is no surprise that having a place to call home with all that means in comfort and security is the #2 reason.

3. It allows you to have more space for your family

Whether your family is expanding, or an older family member is moving in, having a home that fits your needs is a close third on the list.

4. It gives you control over what you do with your living space, like renovations and updates
Looking to actually try one of those complicated wall treatments that you saw on Pinterest? Want to finally adopt that puppy or kitten you’ve seen online 100 times? Who’s to say that you can’t in your own home?

The 5th reason on the list, is the #1 financial reason to buy a home as seen by respondents:

5. Owning a home is a good way to build up wealth that can be passed along to my family

Either way you are paying a mortgage. Why not lock in your housing expense now with an investment that will build equity that you can borrow against in the future?

Bottom Line


Whether you are a first time homebuyer or a move-up buyer who wants to start a new chapter in their life, now is a great time to reflect on the intangible factors that make a house a home.